
Prediction podium
Calls worth owning.
I’ve made calls that were early, nonconsensus and materially right. I’m going back through the archive to document the strongest of them with the original language, date and outcome.
Portfolio ThinkTank
Some are testable forecasts. Others are investment theses. Put your own judgment on the record.
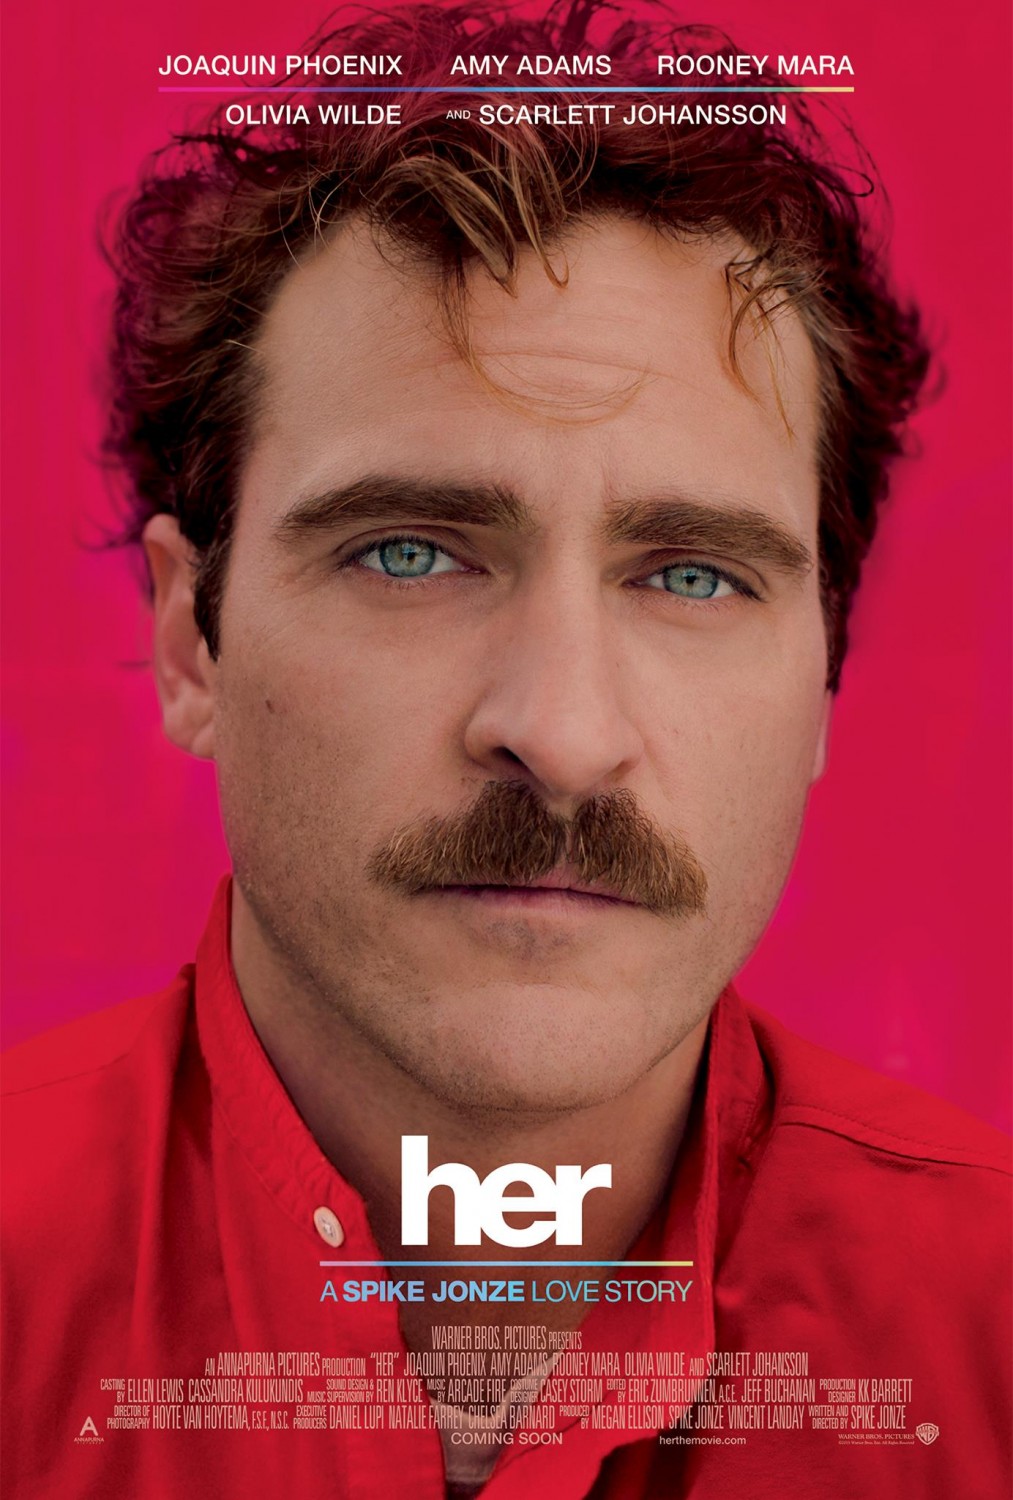

Poster sources: Her / IMP Awards · The Terminator / Film Art Gallery
The future will look much more like Her than The Terminator.
Does this thesis hold?
The SaaS apocalypse is real—and it will be concentrated in high-margin, high-ticket enterprise software and services.
Does this thesis hold?
NVIDIA will remain the investor bellwether for AI in 2027—but not in 2028.
Does this thesis hold?
OpenAI and Anthropic will both complete successful IPOs by the end of 2028. Each will trade above its IPO price one year after listing, and by the end of 2030 their combined market capitalization will equal at least 5% of the S&P 500’s aggregate market capitalization.
Anthropic will briefly command a market capitalization twice that of OpenAI before the relationship reverses.
AI will reverse the great public-company shrinkage. By slashing the regulatory, compliance and audit costs of going—and staying—public, the number of U.S.-listed companies will roughly double by 2036.
Robotics will become AI’s third act: first models, then agents, then machines.
Does this thesis hold?
AI will be profoundly deflationary—and U.S. CPI still won’t turn negative through 2030.
Once the first wave of AI investor enthusiasm peaks, the correction will be fast, deep and short-lived compared with the telecom and internet busts of 2000. Savvy investors will recognize it as a classic buy-the-dip opportunity.
Does this thesis hold?
By 2027, AI strategies will become a fiduciary imperative.
Does this thesis hold?
The great AI trade will rotate from intelligence scarcity to implementation scarcity.
Does this thesis hold?
Data-center REITs and infrastructure credit will be AI’s canary. The first $10 billion AI-infrastructure failure will be a balance-sheet failure, not a technology failure.
By 2030, finance will be the sector benefiting most from AI—but its lead will be short-lived before healthcare overtakes it.
Does this thesis hold?
As generic data becomes cheaper, the most valuable proprietary company data won’t be for sale. It will be worth more kept private as a competitive asset than monetized directly.
Does this thesis hold?
AI will expand the side-hustle and freelance economy without replacing the employee economy. By 2030, U.S. nonemployer-business receipts will have grown faster than employee compensation, while self-employment remains below 15% of total employment.
AI will accelerate technocratic income disparity.
Does this thesis hold?
Asset-heavy businesses capable of generating both top-line growth and margin expansion will enjoy a sustained period of investor favor during AI’s second wave.
Does this thesis hold?
AI will strengthen monopolistic business models built on network effects, scarce resources and calcified distribution.
Does this thesis hold?
Global income and wealth inequality will worsen through 2029, then begin a reversal cycle lasting more than 30 years.
Does this thesis hold?
Humanity will benefit from a true energy breakthrough before 2035, leading to a monotonic decline in global reliance on hydrocarbons—and not a moment too soon for the planet.
Does this thesis hold?
By 2030, we will have a much clearer understanding of the upper boundaries of investment forecasting.
Does this thesis hold?
AI will trigger Smart Beta’s second wave. By 2029, it will become materially easier to prove whether fiduciaries have minimized uncompensated risk, and courts will begin treating avoidable uncompensated risk in cap-weighted portfolios as a measurable fiduciary problem.
The enormous performance gaps investors have grown accustomed to—between winning and losing stocks, sectors and markets—will begin to compress. Global markets will enter an era of shrinking return dispersion.
Does this thesis hold?
Democrats will win back the presidency in 2028, officially resuming the era of globalization.
AI agents will break the seat-based software pricing model. Software pricing will migrate toward usage, outcomes and economic value created.
Does this thesis hold?
Net-margin change will prove to be one of the strongest financial-statement signals separating AI’s winners from its losers—a pattern the Gravity Lens prediction model is already detecting consistently.
Does this thesis hold?
A note from James
If I’m going to make predictions in public, I should also be willing to keep score in public.
Over the course of my investment career, I’ve made some frankly excellent calls—early, nonconsensus calls that mattered. I’m proud of them, and I’ve probably been too quiet about them. I’ve also missed. Sometimes I was early; sometimes the thesis was simply wrong. Both belong in the record.
This page is becoming a living ledger, not a one-time list. New predictions will go on the record as I make them. As outcomes become knowable, the strongest calls will earn their place on the podium and the misses will be documented just as plainly: original thesis, original date and no hindsight edits.
Prediction podium
I’ve made calls that were early, nonconsensus and materially right. I’m going back through the archive to document the strongest of them with the original language, date and outcome.
The misses
Some calls were early. Some were wrong. I’ll document those as well, because a forecasting record that edits out its misses is marketing, not evidence.
Gravity Lens
Gravity Lens is the next step in that progression. I’m no longer interested only in making individual predictions. I’m building a prediction system that learns which inputs are themselves capable of forecasting investment performance.
That distinction matters. The system tests changes in financial statements, market behavior, valuation, risk and other company-level evidence. It looks for signals that remain useful outside the period in which they were discovered, then learns how those signals interact. Net-margin change is one example now surfacing repeatedly as a material divider between likely AI winners and losers.
Gravity Lens is both a model and a research program. It asks the question underneath the stock pick: What has the market not fully priced yet, and which measurable evidence could have told us sooner? That opens worthwhile lines of inquiry for investors, fiduciaries, researchers and companies—not just about where performance may come from next, but how much confidence any forecast deserves.
— James DamschroderFounder, Portfolio ThinkTank